म्युच्युअल फंड
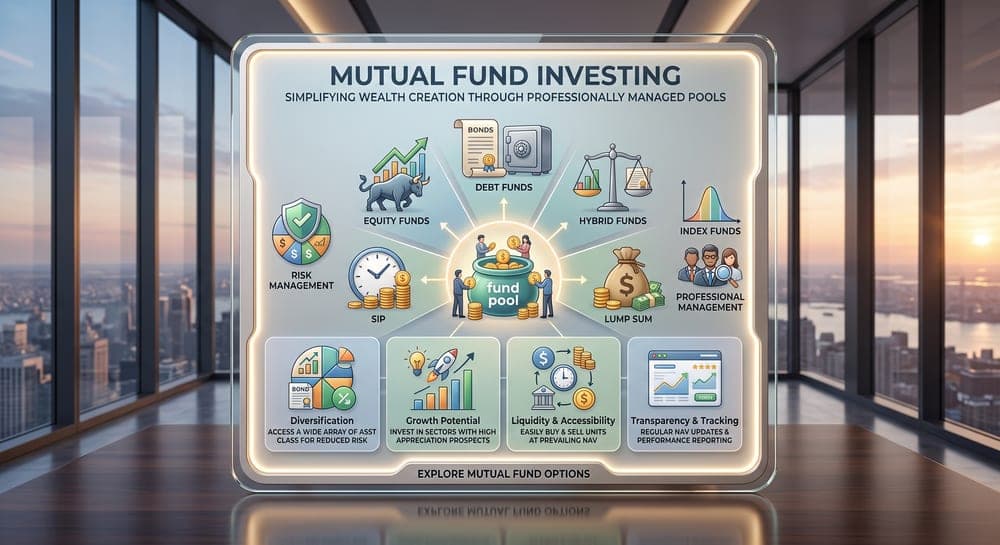
इक्विटी, डेट, हायब्रिड आणि इतर प्रकारांतील व्यावसायिकरीत्या व्यवस्थापित गुंतवणूक पर्याय जाणून घ्या.
म्युच्युअल फंडातील गुंतवणूक बाजारातील जोखमींच्या अधीन आहे.
म्युच्युअल फंड जाणून घ्यागुंतवणूक बाजारातील जोखमींच्या अधीन आहे. योजनेसंबंधित सर्व दस्तऐवज काळजीपूर्वक वाचावेत.
Our services
Each category below is regulated differently and carries its own risks. We describe what each one is and what it involves, so you can judge whether it belongs in your plan.
इक्विटी, डेट, हायब्रिड आणि इतर प्रकारांतील व्यावसायिकरीत्या व्यवस्थापित गुंतवणूक पर्याय जाणून घ्या.
म्युच्युअल फंडातील गुंतवणूक बाजारातील जोखमींच्या अधीन आहे.
म्युच्युअल फंड जाणून घ्या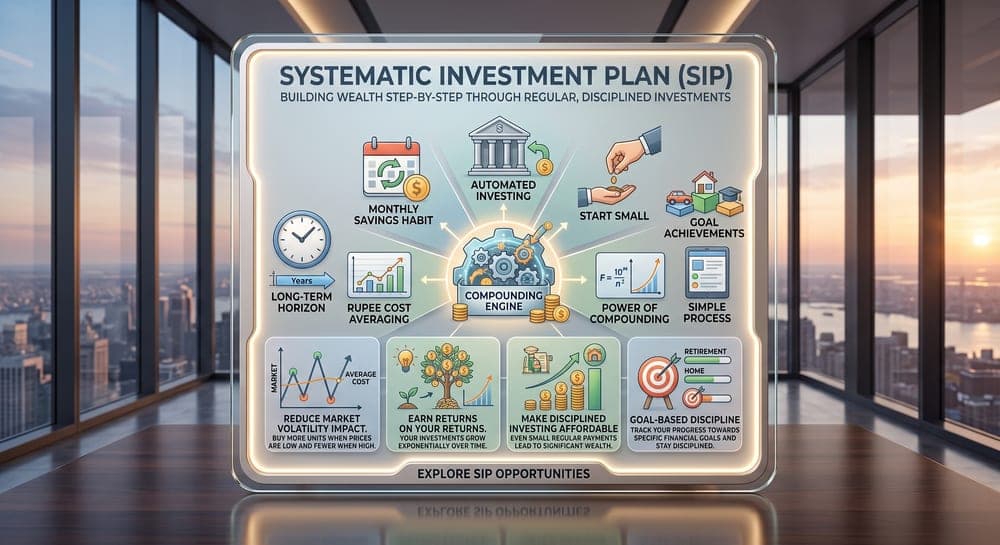
तुमच्या आर्थिक उद्दिष्टांशी सुसंगत नियमित गुंतवणुकीतून शिस्तबद्ध गुंतवणुकीची सवय लावा.
SIP ही गुंतवणुकीची एक पद्धत आहे. ती नफ्याची हमी देत नाही आणि तोट्यापासून संरक्षणही करत नाही.
नियोजन सुरू करा
तुमच्या आर्थिक गरजांनुसार आखलेल्या विमा पर्यायांतून स्वतःचे आणि कुटुंबाचे संरक्षण करा.
पॉलिसीच्या अटी, शर्ती आणि अपवादांच्या अधीन.
संरक्षणाचे पर्याय जाणून घ्या
तुमची संपत्ती व्यवस्थापित करण्यासाठी आणि वाढवण्यासाठी सुसूत्र दृष्टिकोन विकसित करा.
संपत्ती पर्याय जाणून घ्या
पात्र गुंतवणूकदारांसाठी पोर्टफोलिओ व्यवस्थापन पर्याय जाणून घ्या — लागू नियम आणि गुंतवणुकीच्या अटींच्या अधीन.
पात्रता निकष आणि किमान गुंतवणूक मर्यादा लागू आहेत. परताव्याची कोणतीही हमी नाही.
अधिक जाणून घ्या
पात्र गुंतवणूकदारांसाठी पर्यायी गुंतवणुकीच्या संधी जाणून घ्या — लागू नियम, योग्यता आणि किमान गुंतवणुकीच्या अटींच्या अधीन.
अधिक जोखीम, मर्यादित तरलता आणि किमान गुंतवणुकीच्या अटी लागू आहेत.
AIF जाणून घ्याभविष्यातील रुपयांत निवृत्तीचा खर्च किती असू शकतो, आणि कॉर्पस उभा करून नंतर त्यातून रक्कम काढण्यासाठी काय लागते ते जाणून घ्या.
निवृत्तीचे नियोजन कराशिक्षणाच्या महागाई दराने शिक्षण खर्चाचा अंदाज घ्या, आणि पैशांची गरज ज्या तारखेला असेल त्यानुसार नियोजन करा.
शिक्षणाचे नियोजन करामहागाईसोबत वाढणाऱ्या, ठरलेल्या तारखेच्या कौटुंबिक खर्चाचे नियोजन करा — तुमच्या इतर दीर्घकालीन उद्दिष्टांवर परिणाम न होऊ देता.
या उद्दिष्टाचे नियोजन करातुम्हाला काय आणि केव्हा साध्य करायचे आहे तिथून सुरुवात करा — आणि मग त्याला आधार देऊ शकणाऱ्या गुंतवणुकीपर्यंत पोहोचा.
उद्दिष्ट नियोजन जाणून घ्याभारतात वेगवेगळ्या उत्पादनांवर कर कसा आकारला जातो, आणि करआकारणीचा तुमच्या हातात प्रत्यक्ष उरणाऱ्या रकमेवर कसा परिणाम होतो ते समजून घ्या.
करआकारणी वैयक्तिक परिस्थितीवर अवलंबून असते आणि बदलू शकते. हा कर सल्ला नाही.
कर-कार्यक्षमता समजून घ्याउपलब्ध पर्याय, त्यांच्यातील फायदे-तोटे आणि प्रत्येक पर्याय तुमच्या परिस्थितीत कसा बसतो यांबद्दल मार्गदर्शन.
आमच्या टीमशी बोलाअल्पकालीन चढ-उतारांमागे धावण्याऐवजी, दशकांमध्ये संपत्ती उभी करण्याचा शिस्तबद्ध, आढाव्यावर आधारित दृष्टिकोन.
आमचा दृष्टिकोन जाणून घ्याIn more detail
Plain explanations of what each service involves, including what it does not do.
Goal-based planning starts from the outcome rather than the product. A goal needs three things to be planned: a rupee figure in today's money, the date the money is needed, and an honest view of what you can commit each month.
Once those exist, inflation gives you the future cost, and the time available narrows the sensible range of investments. Two goals of the same size but different dates are usually funded very differently.
Retirement is the largest goal most people fund, and the only one with no borrowing option. It has two distinct phases: accumulating a corpus while working, and drawing it down afterwards without exhausting it.
The accumulation phase is arithmetic. The drawdown phase is where most plans are underestimated, because withdrawals have to keep rising with inflation while the remaining balance still has to last.
Education has an immovable date. A child turns eighteen whether or not the corpus is ready, which makes this one of the few goals where the deadline cannot be renegotiated.
Education costs in India have historically risen faster than headline inflation, which is why our education calculator keeps education inflation as its own separate input rather than reusing a general figure.
A wedding is a dated, inflation-linked family expense. Planning for it in advance keeps it from being funded by disturbing long-term investments or by borrowing at short notice.
The planning approach makes no assumption about who is getting married or what the event should look like. You set the scale; the arithmetic follows from it.
Every return you see quoted is a pre-tax number. How much reaches you depends on the category of investment, how long you held it, and whether tax falls each year or only when you sell.
Tax efficiency is a consideration, not an objective. An investment that suits your goal and attracts some tax is a better outcome than an unsuitable one chosen because it is taxed lightly.
Tax rules, rates and holding periods change, and their effect depends on your individual circumstances. Nothing on this website is tax advice. Please consult a qualified tax professional about your own position.
Most financial decisions are not a choice between a good option and a bad one. They are a trade-off — between liquidity and return, between certainty and growth, between what a goal requires and what you can bear.
Our role is to lay out those trade-offs clearly, explain what a product actually does, and be direct about what it costs and what can go wrong.
Wealth is usually built by a modest amount invested consistently for a long time, reviewed periodically, and left alone in between. It is rarely built by identifying the right thing at the right moment.
The hard part is not the arithmetic. It is staying invested through the periods when doing so feels unwise — which is precisely when the discipline matters most.
Life goals
Each of these has a calculator attached, so you can see the arithmetic before you speak to anyone.
शिक्षणाच्या भावी खर्चाचा अंदाज घ्या आणि आज तुम्हाला किती गुंतवणूक करावी लागू शकते ते समजून घ्या.
भविष्यातील रुपयांत लग्नाचा खर्च काढा आणि तुमच्या इतर उद्दिष्टांवर परिणाम न होऊ देता त्याचे नियोजन करा.
तुमची आजची जीवनशैली दशकांनंतर किती खर्चिक होऊ शकते, आणि त्यासाठी काय लागेल ते समजून घ्या.
डाउन पेमेंटचे नियोजन करा, आणि संपूर्ण कालावधीत गृहकर्जाची किंमत किती पडेल ते समजून घ्या.
बाजाराच्या प्रत्येक टप्प्यात शिस्तबद्ध गुंतवणुकीतून हळूहळू संपत्ती उभी करा.
तुमची जीवनशैली पगारावर नव्हे तर तुमच्या गुंतवणुकीवर चालू शकेल, त्या टप्प्याकडे वाटचाल करा.
संपत्तीची उभारणी. भविष्याची सुरक्षा.
तुम्ही भविष्यासाठी गुंतवणूक करत असाल, निवृत्तीचे नियोजन करत असाल, कुटुंबाचे संरक्षण करत असाल किंवा दीर्घकालीन संपत्ती उभारत असाल — तुमच्या आर्थिक उद्दिष्टांना अनुरूप पर्याय शोधण्यात इनामदार वेल्थ तुम्हाला मदत करू शकते.
गुंतवणूक बाजारातील जोखमींच्या अधीन आहे. परताव्याची हमी नाही. कोणतीही चर्चा शैक्षणिक स्वरूपाची असते आणि ती कोणतेही आर्थिक उत्पादन खरेदी किंवा विक्री करण्याची शिफारस नाही.